LPA Leverages Its CRE Market Expertise And Industry-Leading Technology To Research The COVID-19 Pandemic’s Effect On Property Values Across Texas And The Southwest
The United States has weathered a dozen recessions since World War II. However, the financial crisis brought on the novel coronavirus is unlike any we’ve ever experienced. It has brought the economy to standstill seemingly overnight.
Although commercial real estate (CRE) has held its value better than other asset classes during previous downturns, it has not been immune from COVID-19. Deals have been put on pause as buyers, sellers, and lenders step back to reassess the market. Consequently, the flow of sales and rent information (or comps) has slowed to a trickle. As Mark Lowery, LPA’s CEO and President, puts it, CRE valuation experts currently have “almost no post-pandemic data points” to analyze.
This data gap has made the appraisal process both more arduous and less efficient. COVID-19 has forced appraisers to rely more heavily on interviews with market participants to measure transaction frequency and volume. Although the intelligence gathered during these interviews has value, it also has real limitations. Being subjective, it cannot serve as a guarantee of accuracy to the same extent that comps can. “Interviews are anecdotal, and the numbers reported in any given interview are generally not statistically meaningful,” Mark explains.
Having recognized this data gap, our organization mobilized to fill it. We started by identifying the most pressing questions currently facing CRE appraisers.
- How is the market slowdown impacting the value of specific property types?
- How are economic conditions affecting business’ net operating income and, by extension, cap rates?
- Have stay-at-home orders, business interruptions, and record unemployment led to significant changes in occupancy rates?
- When do brokers, lenders, appraisers, and other industry stakeholders in the industry believe Americans will be out of quarantine and back to work?
- Despite the market uncertainty created by COVID-19, have CRE professionals recently heard any good news, observed any positive developments, or been presented with any unique opportunities?
- How can valuation experts quantify this prevailing market sentiment?
We ultimately decided that the best way to answer these questions was via a survey instrument. In conjunction with the questionnaire itself, we built a technology platform to ingest, synthesize, and analyze the resulting data points. On the front end, our web development team created a user-friendly landing page that allowed survey participants to describe their experiences in the field. On the back end, our software engineers linked these survey responses to a database housed on our internal server.
We then kicked off an extensive outreach effort. We knew our data set would be compromised unless we could secure the participation of a large, representative sample population. Our leadership established various incentives — from friendly competitions to bonus programs — to encourage team members in every LPA office and at every level of the organization to spread the word about the survey’s availability throughout their professional networks.
We ultimately collected over 1,000 data points. Under the direction of LPA Manager and project coordinator Drew McFarland, Associate Jake Allen led the effort to analyze this data. Summer Interns Samantha Graves and Cassidy Springer assisted with this process.
Next, our creative team began brainstorming how best to present the results of our survey. The preliminary results reported by Drew, Samantha, and Cassidy indicated that data visualization would be an optimal way to demonstrate COVID-19’s dramatic, real-time impact on the CRE market. Yet the responses we had received also contained several stories compelling enough to warrant inclusion in our final report. Additionally, we knew we wanted this report to be brief and tightly focused on the most actionable pieces of business intelligence we could derive from the survey responses.
After further discussion regarding layout, formatting, and delivery methods, we prepared a template that would allow readers to extract the most value from the insights contained within the report. “Our clients expect us to provide them with accurate and up-to-date opinions of value for their commercial real estate collateral,” Mark says. “The fact that we’re in the midst of a black swan event that has sent shockwaves through every industry hasn’t led to any lowering of those expectations. So we were extremely pleased when we saw the fruits of our labor on this project. We immediately realized that we had something quite special on our hands — a statistically meaningful, highly applicable set of data covering a wide geographic area.”
Our Southwest COVID-19 Survey Summary Report is now available as a free download. Whether you participated in our survey or not, we invite you to review its key findings, factor them into your own planning and CRE portfolio management efforts, and share them with your fellow decision-makers. We also welcome any feedback you may have about the report.
As efforts to safely reopen the economy enter a new phase, we will continue to augment our research capabilities. Later this year, we will release custom survey reports for each of the major Texas markets in which we operate. We’ll also be conducting a second round of interviews focused on our industry’s recovery from the financial toll taken by the pandemic. Finally, we’ll be expanding to a new market — El Paso — and surveying its CRE experts.
In closing, we’d like to express our gratitude to everyone who helped make this research project a success. To the members of our LPA family: thank you for stepping up with energy and fortitude. To our fellow CRE professionals: thank you for your willingness to participate in our survey and the generosity of your responses. And, to our clients: thank you for letting us continue to serve you.
Much has changed in the last two months. We’ve all had become conversant with social distancing etiquette, strike a new balance between home and work life, and cope with the fact that some business, while it may feel urgent, does not qualify as essential.
Adjusting to the shifting circumstances surrounding COVID-19 hasn’t always been easy. Most days, silver linings are in short supply. Here at LPA, however, we’ve tried to keep our vision trained on the North Star that’s guided us since our founding: our Core Values.
In the process, we’ve come to appreciate all over again just how much our people’s commitment to Excellence, Teamwork, Integrity, Selfless Service, Family, and Innovation allows us to deliver commercial real estate valuations of impeccable quality. But we’ve also had to stretch ourselves to ensure that these Core Values remain as meaningful and purposeful as possible.
In short, the past two months have been a learning experience. As we look to the near future and, like millions of other Texans, plan on returning to our offices, we’d like to impart the lessons we’ve learned from our time in quarantine. We believe the best way to do that is to share with our Insights readership the recent revisions we’ve made to our Core Values, as well as some examples of how we’ve put them into action.
Excellence
In the face of COVID-19, we’re working hard to achieve Excellence. We’re obtaining the most up-to-date market data to produce the most credible, actionable valuations for our clients. In such a rapidly changing environment, this is a tall order. We’re up to the challenge!
Teamwork
At LPA, Teamwork is paramount. Each of our Teams is holding multiple meetings each week via phone, email, and video chat. Additionally, our Management Team is holding two video chat meetings every week to ensure that the entire staff remains at the forefront of everything happening in the our industry.
Integrity
This Core Value is front and center in our profession! We’re boldly yet humbly developing opinions of value for our clients to assist them in making the most well-informed decisions. During these uncertain times, unwavering Integrity is priceless.
Selfless Service
LPA has established a fund to match donations made by our Team members to the COVID-19 charity of their choice. At the outset of the quarantine, LPA supported local restaurants by buying lunch for our staff and their families to be delivered to their homes.
Family
100 percent of LPA’s current staff is currently working from home full-time. We acknowledge that each Team member has their own family structure and familial obligations to meet. During this time (and through the coming weeks and months), LPA will be accommodating the individual needs of each Team Member and will do what is required from an organizational standpoint to protect both they and their families.
Innovation
LPA has launched a COVID-19 Market Survey. This tool will allow our Team members to combine data crowdsourced from market participants with information entered by a diverse cohort of CRE valuation users. Our goal with this project is to gauge (to the best of our ability) the real-time impact COVID-19 is having on CRE values. If you would like to participate in this survey, please visit https://fm.lpa.com/covid-19-survey/#/.
As always, thank you to our Team members for all their hard work and dedication, and to our clients for their continued support. We’re all in this together — and, together, we will overcome whatever challenges remain.
As a nation, we are now about a month into an extended socioeconomic experiment. We are all learning social distancing etiquette, adjusting to the idea that some businesses are essential (and others not), and coping with anxieties we could not have imagined feeling mere weeks ago.
Yet some of the uncertainties we covered in our last installment of Insights have been since dispelled. Whiplash is no longer a fact of life for traders on Wall Street. Public health officials are beginning to gain a better understanding of the scope and scale of the COVID-19 infection — not to mention the efficacy of the unprecedented measures taken to “flatten the curve.” And, on March 27, 2020, President Trump signed the Coronavirus Aid, Relief, and Economic Security (CARES) Act into law.
This $2-trillion stimulus package carries only a few CRE-specific provisions, nearly all of them directly impacting landlords and tenants. Businesses can apply for forgivable loans to help them cover rent, utilities, and even mortgage interest. Further, multifamily borrowers with federally backed loans can request a 90-day forbearance. The CARES Act also places a 120-day moratorium on evictions from public housing or properties secured by a government-sponsored enterprise (GSE).
More importantly, the CARES Act signals a renewed willingness on the part of Congress to intervene in our economy. Additional phases of legislative response are being debated even now, including a jobs program focused on infrastructure. Such a sweeping initiative could have a profound impact on the construction industry.
What else might the future hold? What are CRE experts seeing as they eagerly look forward to the end of the present crisis?
“The real estate industry is being clobbered by the coronavirus, and it’s going to get worse before it gets better.”
So writes Brad Hunter, Managing Director for RCLCO Real Estate Advisors, in Forbes.
What accounts for his pessimism? Hunter is particularly concerned about regional “hot-spots” like Florida, whose economy relies so much on out-of-state tourism.
“Florida, for example, is exposed across a number of important industries, including:
- Hotels
- Theme Parks
- Conference Centers
- Casinos
- Sports Venues
- Restaurants and Bars
- Cruise Ships
Additionally, it remains to be seen how Florida’s congregate senior housing industry will be impacted.”
But Texas makes Hunter’s list as well, primarily due to the steep drop in oil prices — and accompanying “economic drag” — that has accompanied the COVID-19 outbreak.
Does Hunter see any silver lining? Perhaps in multifamily. Again, Hunter is worth quoting at length on this topic.
“The long-term outlook for rentals is still bright, however, in light of demographic shifts that are still unfolding. Lease renewal rates were strong before the crisis, and apartment construction was running at more than 500,000 units annually right before the crisis, so it has some ground to give. Class ‘B’ properties will likely fare better than expensive ‘A’ properties or Class ‘C’ developments that may be more susceptible to job losses and lost income among tenants… The single-family-built-for-rent business might be a long-term beneficiary as we may see a shift toward larger units that better accommodate working from home (allowing more space for a home office or office nook).”
“Forecasting models are simply not designed to capture this scenario.”
That’s the note of caution sounded by Andrew J. Nelson, CRE. Yet he follows a more optimistic trajectory than Hunter, going on to say that “the best course of action for most market participants is to defer major decisions until there is greater clarity as to market directions.”
To help provide that clarity, Nelson has also conducted a thorough, sector-by-sector overview, examining both the short- and long-term prospects for a variety of property types. While several industries have been hit especially hard already, Nelson does call the CRE community’s attention to conditions that may spell immediate trouble in multifamily.
“Also vulnerable in the very near term are two demographically-favored niches that have been the darling of investors: student housing and senior housing. Student housing especially is likely to see financial strains as college campuses are closed, and students are sent home. And senior housing may see a short-term drop in demand as vulnerable older Americans shelter-in-place to reduce the likelihood of contracting the virus. However, both should see a rapid snap back in demand as the crisis eases.”
Meanwhile, Nelson notes, some landlords experiencing acute pain right now may be feeling relief once something resembling normal economic activity resumes. Consider co-working spaces, which are facing lost revenues that traditional office buildings managing one-, two-, and five-years leases are not.
“We might also anticipate a sharp and permanent shift to telecommuting, to the long-term detriment of traditional office leasing… But some of the shift will prove permanent as firms learn to work remotely and are making material investments in telecommuting infrastructure to ensure their business can succeed with at least some of their employees working remotely. Thus, expect firms to continue the long-term trend of reducing the amount of office space leased per worker. One beneficiary should be flex-office space, as workers needing quiet space outside of the home seek affordable workplaces near-by.”
Rapid changes in consumer behaviors are also reshaping the CRE landscape, Nelson writes, and with implications that reach far beyond retail.
“These shifts [in buying patterns] will continue to benefit the industrial property sector, particularly logistics and last-mile facilities, as retailers and manufacturers deliver goods directly to consumers at home. After a short drop-off in leasing during the shutdown, expect a rapid bounce back. Not all facilities will benefit equally, however. The pandemic has laid bare the risks to producers associated with global supply chains. Expect the nascent trend to “near-shoring” to gather strength in favor of more localized suppliers. Thus, we may see some shift from port-focused warehousing to those closer to domestic manufacturing centers.”
Yet, as the Federal Reserve Bank of Dallas reported at the end of March 2020, manufacturing in the Lone Star State has come to a virtual halt, and abruptly.
“The production index… plummeted from 16.4 to -35.3, suggesting a notable contraction in output since last month. … The new orders index dropped to -41.3… Similarly, the growth rate of orders fell to 44.9. The capacity utilization and shipments indexes fell to -33.43 and -33.8, respectively… Other indexes for future manufacturing activity also fell sharply into solidly negative territory.”
These are bellwether numbers, as Texas accounts for about 10 percent of domestic manufacturing. Therefore, even those more local supply chains are not immune from the effects of this pandemic. What our state’s experience augurs for industrial — one of the most in-demand property types entering 2020 — over the next three to four months bears watching.
“I’m hearing that one-third of the deals are dying, one-third are pausing, and one-third are still happening.”
From Kidder Mathews’ President Brian Hatcher’s perspective, this split is not abnormal. “Compare [it] to 2008 through 2010 when there was absolutely nothing happening. If everything stays on course here, I think this might be the easiest downturn we have. I say ‘if’ with a capital ‘I.’”
Hatcher also asks us to conceive of the current circumstances as a slowdown rather than a downturn. “Any deal with a retail component is going to get a lot more scrutiny than perhaps it has in the last five years,” he says. “This disruption will make everybody check themselves and pause.”
But are such “big picture” takes examining these issues through the right lens? Forbes Senior Contributor Mayra Rodriguez Valladares is not confident that they are.
“In my view, it is also important that investors, analysts, and regulators look more at the fixed income market, which includes sovereign debt (Treasurys), municipal debt, corporate debt, and asset-backed securities, which… includ[e] leveraged loans, residential and commercial mortgages, student loans, auto loans, and credit cards… Investors in corporate debt are certainly signaling that they fear that defaults are imminent, especially in those corporations whose rating is speculative… [Meanwhile,] [a]lready, before the COVID-19 crisis, consumer delinquencies had started to rise.”
The upshot? “I am more and more convinced that the COVID-19 crisis will be far worse than the 2008 financial crisis,” Valladares admits. But she has not completely given up hope. “With any luck, it will be shorter-lived.”
If that’s true, where might we turn to see the first signs of economic recovery?
“The core takeaway from the pandemic’s geography — measured in COVID-19 cases, county-by-county — is that of clustering.”
According to HousingWire‘s Editor at Large Kathleen Howley, that recovery will have to first come to those regions of the U.S. caring for the largest populations of COVID-19 patients. Her reasoning?
“The nation’s COVID-19 infections concentrate in a short list of economically central, often job-rich counties on the coasts and the Great Lakes region. The nation’s 50 hardest-hit counties support more than 60 million jobs and $7.4 trillion in economic output, good for 30% of the nation’s employment and 36% of its GDP.”
In this one observation, public health and economics intersect to reveal why COVID-19 poses such a risk to our nation’s financial health. Those large, densely-populated metropolitan areas most susceptible to the spread of an airborne disease also happen to be, in Howley’s words, “most central to driving the nation’s big-city, globally networked economy.”
In a recent editorial penned for The Dallas Morning News, Professor Steven Pedigo of the Lyndon B. Johnson School of Public Affairs at the University of Texas at Austin echoes this sentiment, then gives it a local spin.
Major disruptions tend to accelerate existing trends. Already, 8 out of 10 Texans live in cities and metropolitan areas, which run the gamut from global centers like Dallas, Fort Worth and Houston to startup hubs like Austin, border cities like El Paso, college towns, and oil patches.
Our Texas cities will become ever more important, because the same things that made them vulnerable to COVID-19 — their international connectivity, dense living patterns, and gathering spaces — will also make them the engines of our recovery, powered by the cutting-edge industries that cluster in them, like software, fin-tech, tech-driven manufacturing, aerospace and renewables.
Nevertheless, those of us who survived the Great Recession may be concerned that CRE is headed for the same fate: collapse. But, while Andrew J. Nelson sees real challenges ahead for capital markets (especially alternative lenders), he also reminds us that the COVID-19 crisis is fundamentally different from the one we witnessed in 2008-2009.
“Perhaps the best news on the financing front is that leverage rates overall tend to be much lower now… Moreover, construction in most markets has been more moderate in this cycle than is typical, yielding strong property fundamentals with record-low vacancy rates, despite relatively modest space take-up. Thus, depending on the severity of the downturn, defaults and bankruptcies may be less likely this time around as most financed properties have more fiscal room to absorb revenue declines.”
Brad Hunter makes a similar point.
“Unlike in the Great Recession, once the virus is contained and immunity starts to take hold in the population, even though supply chains will take some time to re-engage, it may not feel like the cold start that followed the housing and mortgage crash. The cycle could look like a ‘V,’ or possibly more of a narrow ‘U,’ with a sharp drop but also a strong upswing, coming at some time in the second half of this year.”
In other words, the economy may bounce back in dramatic fashion, with those areas of the U.S. where CRE has proven to be most resilient over the past decade leading the way.
When we first entered 2020 a little over two months ago, commercial real estate across the U.S. was enjoying a very rosy outlook.
Then came coronavirus disease 2019 (COVID-19).
If China’s experience is any indication, the full economic impact of this pandemic will probably not be measurable for months. What we do know, however, is that markets everywhere are coping with profound uncertainty. How long will the outbreak last? How will efforts to protect public health, centered as they are around “social distancing,” affect consumer behavior? Is a recession imminent, or has one already begun?
LPA’s resident thought leaders have been tracking the COVID-19 situation since January. Although we can’t hope to answer all of the CRE-related questions our clients and partners might have in this one article, we have endeavored here to share the best business intelligence we’ve gathered thus far.
As you might imagine, what follows is a mix of good and bad news. In the former category: CRE is likely to remain among the most resilient assets in any coming economic downturn. In the latter: landlords, developers, and lenders whose holdings include certain property types can expect to feel some acute short-term pains.
Supply chain disruption impacts industrial inventory
While efforts to contain COVID-19 continue to ramp up across the United States, day-to-day life is trending back toward something resembling normality in China and South Korea. Consequently, we’re only now getting a glimpse of what the virus has done to their manufacturing sectors. In January and February 2020, China’s industrial production declined by 13.5 percent.
To place that number in context, consider this observation from a Transwestern report published just last month: “In February, U.S. port volumes are projected to be nearly 13 percent lower when compared with the same period last year and 9.5 percent lower in March.”
What does this mean for warehouses and distribution centers? Moody’s Analytics now expects real GDP growth to settle in below its 2 percent potential growth rate: 1.5 percent. Nevertheless, this supply chain issue doesn’t mean a wholesale shift in industrial leasing is to follow. As Moody’s further notes, “[t]he delivery of goods and services may be delayed, but it is unlikely that long-term leases of industrial buildings (with some stretching to 20 years) will be renegotiated (unless a wide-scale rash of business bankruptcies and a major global recession ensues).”
Remote work has staying power
If you haven’t been instructed to work from home in the last week, then it’s likely that you know several people who have. At the moment, full-time remote work makes up less than 5 percent of all U.S. jobs. That figure may seem low based on anecdotal evidence, but, as Sara Sutton, the founder of job listing site FlexJobs, notes, “[a] lot of organizations are doing remote work right now in a very ad hoc manner,” making precise measurements — not to mentions projections — tricky.
However, should employers adopt a more concerted and organized approach to work from home (WFH) arrangements, the demand for office space could decline. The same holds if, after the initial growing pains of pivoting to WFH subside, businesses realize that white-collar job performance in particular may not be adversely affected by lack of access to a traditional office.
Either way, companies everywhere are about to get a crash course in both the benefits and disadvantages of remote work. Until all of those pros and cons have been sorted out, it is unlikely that we will see a massive, permanent shift in where Americans conduct their business.
Dramatic curtailment of travel and tourism will hurt more than hospitality and restaurant spaces
It’s no secret that the tourism and travel industries are taking a serious hit during this outbreak. We’ve seen numerous conferences, festivals, and sports leagues either postpone or outright cancel their events. In Austin, SXSW’s cancellation is expected to cost the city $350 million, with event spaces, restaurants, bars, and hotels shouldering the biggest losses. Worse, margins for these industries are already razor-thin. The next cancellation notice they receive can mean the difference between a good year and not making it to 2021.
Travel restrictions also directly impact the CRE industry. Canceled professional conferences, a cap on business travel, and government-mandated “sheltering in place” all make it harder to execute existing or upcoming deals. Will proptech come to the rescue? This is not a science-fiction scenario. For example, to maintain a healthy volume of transactions, CREModels has announced free access to a suite of collaboration tools designed to help CRE professionals keep their negotiations moving toward a close. Watch for other proptech providers to follow suit should the coronavirus outbreak be prolonged.
Money may dry up for some lenders, especially non-banking financial institutions (NBFIs)
It’s too early to tell how ratings for financial institutions will be affected by COVID-19. Yet S&P Global economists have already sounded a note of caution, stating that “particularly under an adverse scenario, we would expect stress on loans to borrowers in areas dependent on consumer discretionary spending (retail, leisure, transport/travel, and infrastructure) or supply chains (autos, technology, and commodities), and in energy.”
These same experts deem it not improbable that “pockets of commercial real estate in certain geographies and asset types, such as retail and office space, could also worsen.” If there is a port in the storm, it might be Net Lease REITs, and thanks to the quality of these properties’ tenants. Nevertheless, even the ability of these assets to bear the brunt of coronavirus-related market uncertainty will be tested.
Rent rebates, already a reality in Asia, could come to the U.S.
If we can treat Asia’s Q1 2020 economic performance as a kind of crystal ball, then tenant relief could be on the horizon. Rent rebates and rent cuts have been implemented in Singapore and Hong Kong to help keep tenants in business as they deal with shutdowns and quarantines.
How big of a rebate or cut? According to Singapore’s The Business Times, “[a] number of mall operators, including CapitaLand, Mapletree Commercial Trust, and Perennial Real Estate Holdings, had announced rental relief in a bid to pass on savings from a 15 percent property tax rebate announced during Budget 2020 to qualifying commercial properties.”
Additionally, CRE stakeholders should not be surprised at local grassroots efforts to place a moratorium on evictions and implement rent freezes and as long as quarantine-like conditions obtain. If so, the impact could extend beyond retail and into the multifamily sector.
Texas can weather economic turmoil better than most regions
Any more good news is welcome at this point, so it’s important to note that Texas is the best-equipped state to handle a recession. According to a study conducted by Fit Small Business, the Lone Star State can claim “the second-lowest debt-to-income ratio in the nation at 1.16, the third-highest total exports per capita, and a diverse range of industries that make up its GDP portfolio. What’s more, its top export countries — Mexico, Canada, and China — are relatively big players in the international trade scene.”
Additionally, the North Texas communities of Frisco, Plano, and Denton recently made the Top 5 in SmartAsset’s rankings of the U.S.’s most recession-resilient cities. The main factors in SmartAsset’s calculations? Employment, housing, and social assistance. With respect to the latter, SmartAsset observes that “Texas performs particularly well for its state’s rainy-day funds as a percentage of state expenditures — ranking second-highest of all 50 states at almost 19 percent.” That augurs particularly well for residents, individual as well as corporate, should the COVID-19 outbreak cause significant financial hardship.
Which has been more greatly exaggerated: reports of a retail apocalypse or a retail revival?
Brick-and-mortar store closures are an undeniable concern for big (and often overextended) brands such as Payless ShoeSource, Forever 21, Pier One, Victoria’s Secret, and others. On the other hand, in their search for growth opportunities, major retailers are increasingly responding to consumers’ health and wellness needs — and reaping benefits as a result.
In 2019 alone:
- Amazon began offering health insurance coverage via its Haven partnership with JP Morgan Chase and Berkshire Hathaway;
- CVS embarked on a nationwide expansion of its HealthHUB initiative;
- and Walmart opened branded health centers in both Atlanta and Dallas.
These last two examples are most relevant to anyone with an interest in commercial real estate (CRE). They point to an explosion of interest in medical retail, more popularly known as medtail. This rising trend in adaptive reuse is helping landlords make up for the departure of many long-standing tenants.
Case in point: late last year, Blue Cross Blue Shield of Texas announced that it would be partnering with Sanitas to care for underinsured and uninsured patients via 10 new clinics across Dallas and Houston. These clinics will focus on value-based primary and urgent care and occupy former retail spaces — for example, a storefront adjacent to a Lowe’s Home Improvement outlet in Richardson, one of Dallas’ first-ring suburbs.
What else do developers, brokers, lenders, and other CRE stakeholders need to know about medtail? Read on to learn why and how medtail will likely remain a market force to be reckoned with in 2020 and beyond.
1) Medtail recognizes that economic opportunity and community health are inextricably linked
It might seem self-evident, but environmental factors have an enormous impact on your well-being. That includes your zip code. Geographic data specific to food insecurity, employment rates, and transportation services combine to be a more telling indicator of a person’s health than his or her genetic code or preexisting conditions.
Ultimately, communities that are home to thriving local economies are healthier overall. In the words of The Pew Charitable Trusts, “efforts to attract business and commercial investment can improve the stability of local economies through job creation, an increased tax base, and enhanced access to necessary goods and services, which affect household income and health outcomes such as stress, chronic diseases, and mental health.”
Medtail represents something of an end-to-end — or holistic — solution in this respect. It makes those “necessary goods and services” more available to underserved populations while filling those vacancies that can contribute to the spread of urban blight. In short, medtail brings healthcare closer to where community members live, work, and shop. This is no small achievement given that approximately 40 million Americans lack what the Centers for Disease Control and Prevention classify as a “usual place” to obtain medical care.
2) Shopping malls and strip centers stand to benefit most from medtail
How have top-line shopping malls like Dallas’ NorthPark Center been so resilient in the age of eCommerce? By retaining their high-end and luxury retail tenants. Unfortunately, that simply hasn’t been an option for mid- and low-tier malls.
80s nostalgia may be all the rage, but department stores, long the anchors of suburban commerce, are no longer driving foot traffic as they did in their Reagan-era heyday. In 2018 (the year such figures were last collected), department store visits were down by approximately 10 percent. Meanwhile, industry experts predict that more than 1,000 department stores will be shuttered by 2023.
Enter medtail. Since 2017, mall leases for medical clinics have risen by almost 60 percent. By comparison, mall leases for apparel retailers have declined by more than 10 percent during that same period. The result has been a win-win. Landlords are happy to find new tenants willing to fill the sizable footprints left by departed department stores. And medical providers, whether they be general practitioners or specialists, get more bang for their buck — the “buck” being affordable rent, and the “bang” being access to a great deal of repurposable square footage.
3) Medtail can soothe providers’ pain points
Patients aren’t the only ones complaining about the rising cost of healthcare. Medical office building (MOB) space is expensive, and rents keeping inching upward to meet demand. Prices per square foot for this property type have hit all-time highs in the past three years, topping nearly $23 in some markets.
Moreover, as healthcare delivery methods continue to advance and diversify, provider expectations regarding desirable location, functionality, and amenities are evolving as well. Yet MOBs are notoriously difficult to renovate — especially structures built prior to the passage of the Americans with Disabilities Act (ADA) in 1990. As Richard E. Juge, CCIM, observes, because the industry has become increasingly consumer-driven, many MOBs may have outlived their usefulness. “While hospital inpatient use is declining,” he writes, “the healthcare industry as a whole is booming with new and different types of facilities: outpatient surgery centers, ambulatory care centers that provide sophisticated imaging procedures such as MRI and CT scanning, geriatric care centers, on-demand diagnostic care centers, primary outpatient service centers, and home healthcare delivery systems. As the industry continues to grow, it will need a greater number and variety of facilities to house these new services.”
Healthcare providers view medtail as an opportunity not only to bring in more patients but also as a chance to relieve themselves of the financial burden that operating in more traditional — and traditionally centralized — MOBs can impose.
4) Some service lines may be more suited to medtail than others
Clearly, not all medtail is created equal. Heath clinics and general practices offer communities the lifelong benefits of preventative care. But, from a CRE perspective, specialized service lines such as dialysis, urgent care, and outpatient services offer the highest capitalization rates (cap rates). According to research conducted by The Boulder Group, urgent care cap rates remain the highest at 7.25 percent. At the same time (through 2019), dialysis centers experienced the most significant bump, rising 15 basis points to 6.15 percent.
Whether operating out of a shopping mall or a single-tenant property, these specific service lines offer long-term, stable leases appealing to many property owners, neighboring businesses, and patients.
5) Ground-floor spaces are especially suited for medtail
Even within malls and shopping centers, location remains a deciding factor in whether or not a particular property is well-suited for medtail. Not as sexy as a new Apple store, an outpatient provider is unlikely to be the focal point of a retail hub. However, it’s also unlikely to be relegated to a second-floor corner far off the beaten track. Medtail is one of the few “internet-resistant” brick-and-mortar property types, and no matter how much self-diagnosing we might attempt via WebMD.
Accessible, ground-floor spaces offer convenience to patients, most notably those with mobility issues. They also increase area foot traffic and promote one-stop shopping. Landlords would be wise to consider these aspects of the customer/patient experience when vetting properties for their medtail potential.
6) Zoning may be an obstacle for medtail in some communities
As plug-and-play as medtail can be for existing locations, there are still ordinances, regulations, building codes, and occupancy requirements to consider. Experienced developers in this sector appreciate how much of due diligence is involved. However, players new to healthcare construction may need to enroll in a crash course in compliance.
For example, the law of the land in Beverly Hills, CA, imposes severe limitations on developers seeking to convert retail to medtail. In the Lone Star State, medical facilities must adhere to Rule §133.162 of the Texas Administrative Code. Landlords and potential tenants should also be prepared to work closely with local Chambers of Commerce and city councils, as well as respond to comments, questions, and concerns from the general public. Overcoming NIMBYism may pose serious challenges for any provider, but especially those specializing in mental health, addiction treatment, and recovery services.
Leader Explains How Texas’ Growing Population and Thriving Economy Are Creating Opportunities Even as They Place a Strain the State’s Infrastructure
It’s no secret that Texas continues to pace the nation in just about every significant measure of economic health. But the latest numbers provide an even more impressive than usual reminder of just how much opportunity is spreading from one end of the Lone Star State to the other.
According to the U.S Census Bureau, more than 367,000 people relocated to Texas between July 2018 and July 2019; staggeringly, that’s more than 1,000 people per day. Meanwhile, the state’s major metropolitan areas — specifically, Dallas and Houston — are expected to trail only the Bay Area/Silicon Valley in GDP growth over the next three years.
In the decade to come, Texas’ relative affordability and steady employment figures will likely continue to attract even more newcomers. These trends are naturally exciting for public and private developers as well. They have a vested interest in making sure the state’s roads, utilities, and communities can accommodate additional residents and new businesses.
We recently sat down to talk with LPA’s right-of-way (ROW) practice leader, Mario Caro, MAI, AI-GRS, SR/WA, and Managing Director at LPA’s San Antonio offices, to learn more about Texas’ thriving economy, its growing infrastructure needs, and the role commercial real estate (CRE) valuation services play in supporting the state’s investment in itself.
The following conversation has been condensed and lightly edited for clarity.
With growth sometimes comes growing pains. By virtue of the work you do, are you seeing evidence of that in Texas? If so, how so?
Absolutely. As more and more rural areas, unincorporated communities, and exurbs get absorbed by Texas’ big cities, transportation and utility departments have a definite need for right-of-way valuation services to keep up with that growth. And it’s not only municipalities that are experiencing these growing pains. Texas’ individual landowners and taxpayers are feeling them, too.
For example, we’re currently working on a proposed 36-inch wastewater line that will pass through rural land bordering a creek in a suburb of San Antonio. This line will ultimately serve newer subdivisions that are popping up in droves. While not everyone may be thrilled about the exercise of right-of-way acquisition, flushing toilets, kitchen faucets, and washing machine hook-ups are all conveniences we’d rather not do without.
So, how do we honor our Texas traditions and preserve our wide-open spaces while continuing to provide the infrastructure necessary for record population growth? It’s a delicate balance that requires a great deal of careful planning. Moreover, we all have to work together to ensure everyone’s concerns are heard and needs are considered. As right-of-way appraisers, we’re very accustomed to talking with different stakeholders (condemnors, real property holders, TxDOT, municipalities, private developers, you name it), seeing things from their perspectives, then coming to an amicable solution. We appreciate that relentless research into market conditions, coupled with insight, experience, and empathy for the landowner’s position, are all key to helping ensure a fair outcome.
Right-of-way (ROW) valuation is not just about protecting the financial interests of our client (the state or county, and ultimately the taxpayers). It’s about using all of the information at our disposal and the expertise we’ve acquired to present appraisals that are beyond reproach. It’s also not uncommon for our appraisers to be called as expert witnesses when legal disputes crop up in right-of-way proceedings. So not only do our appraisals have to be accurate by any objective standard, but our valuation experts must also be able to convey appraisal methodology and techniques to laypersons in a thoughtful and convincing manner. Accuracy is the best way to answer the question, “Are we accounting for action in our market while being impartial to both parties?” — Mario Caro, MAI, AI-GRS, SR/WA, Managing Director, LPA (San Antonio)
How are communities across Texas successfully adjusting to the state’s exploding population?
A good example is what’s been happening down in the Rio Grande Valley. There, several communities [Hidalgo County, Brownsville, and Harlingen-San Benito] recently merged to form their own MPO, or Metropolitan Planning Organization. In doing so, they’ve positioned themselves to reserve a better seat at the same table where Houston, Dallas/Fort Worth, San Antonio, and Austin vie for the allocation of state transportation funds. Representation equals bargaining power, and these local governments are doing what they can to make sure their citizens benefit from that power.
It also helps to understand just how much transportation money is at stake here. Over the next 10 years, Texas expects to spend $77 billion on transportation infrastructure. The bulk of that spending will be dedicated to new and expanded highways. Another way to look at this is that, in 2019, the acquisition budget for TxDOT’s Right-of-Way Division was $800 million. In 2020, that budget is expected to surpass the $1 billion threshold.
We expect that right-of-way acquisition volume will be high, too. An estimated 2,000 to 2,100 parcels will be acquired for right-of-way purposes this year. So, it’s not just that we’re talking about changing funding priorities — how tax dollars are spent. We’re also talking about the road map of Texas itself being redrawn.
What does all this economic growth mean for the state’s big industries?
That’s definitely an emerging aspect to right-of-way, and it’s going to be an even more significant factor moving forward. Take the Port of Corpus Christi. Already a major economic generator, it’s beginning to rival the largest ports in the country. Corpus Christi now ranks third in the nation in terms of tonnage coming in and out. They’ve also risen to the number-one spot among exporters of crude oil. Currently, the Port Authority is dredging and widening its channel to accommodate even bigger shipping vessels and replacing the Harbor Bridge with a taller, more modern structure. The goal is to make Corpus Christi the first stop for freight coming through the Panama Canal.
There’s an oil and gas dimension here, too. With all the oil shale production happening across Texas, that industry is realizing that pipelines are the most efficient midstream solution out there. Pipelines get oil to port and get it ready for final delivery both more quickly and cost-effectively than other methods. So we’re seeing more pipeline right-of-way projects linking the Permian Basin and the Gulf Coast.
How does the right-of-way valuation process help make all this possible?
By being impartial, timely, and accurate — which means being research-driven.
Because our biggest clients, so to speak, are condemning authorities like TxDOT, we have a responsibility to taxpayers to be good stewards of federal and state dollars. But, as a property owner myself, just compensation matters to me, too. So I constantly strive to put myself in the shoes of the person who’s having their land acquired for public use (and, sometimes, condemned) and treat them as I would want to be treated.
Every Texan has something at stake in seeing these projects reach completion in a reasonable amount of time. But these infrastructure projects can be as complex as they are massive. Sometimes, our appraisers find themselves in a time crunch, or they aren’t able to work under optimal conditions. Maybe the project has already experienced delays related to surveying or environmental clearance. In fact, I’ve been working on a project in South Texas, near the border, that’s been on hold for two and a half years. Whatever the case, as appraisers, we never want to be a bottleneck, and we want to make sure our clients are able to stay both within budget and on schedule.
Finally, right-of-way valuation is not just about protecting the financial interests of our client (the state or county, and ultimately the taxpayers). It’s about using all of the information at our disposal and the expertise we’ve acquired to present appraisals that are beyond reproach. It’s also not uncommon for our appraisers to be called as expert witnesses when legal disputes crop up in right-of-way proceedings. So not only do our appraisals have to be accurate by any objective standard, but our valuation experts must also be able to convey appraisal methodology and techniques to laypersons in a thoughtful and convincing manner. To bring this conversation full circle: accuracy is the best way to answer the question, “Are we accounting for action in our market while being impartial to both parties?”
All signs point to 2020 being a very good year for the commercial real estate (CRE) industry. Investor confidence in CRE assets — from retail to industrial — remains high, with some experts projecting that investments for the year could top $500 billion.
Consequently, 2020 may also prove to be the Year of the Opportunity Zone. How so? Read on to learn more about the past, present, and potentially bright future of this novel impact investment vehicle.
What Are Opportunity Zones?
Congress created the Opportunity Zone program when they enacted the 2017 Tax Cuts and Jobs Acts. Its goal is to increase the flow of capital to “low-income” areas (as determined by the U.S. Census Bureau) by incentivizing business development within those communities.
Specifically, the Internal Revenue Service allows those who invest in a Qualified Opportunity Fund (QOF) backing an income-generating Qualified Opportunity Zone Business (QOZB) to defer the tax on their eligible capital gains until the investment is sold (or December 31, 2026, whichever comes first). If the investment is held for five years, a ten-percent exclusion of the deferred amount is added. If the investment is held for more than seven years, that figure rises to 15 percent.
The program offers additional incentives to investors who make a long-term commitment to Opportunity Zones. Once a decade has passed, Opportunity Zone investments become eligible for an increase in basis relative to their fair market value. Further, investors have a 180-day window after acquiring gains to invest them in a QOF and defer the tax on any invested gains until 2047.
Opportunity Zone investments are also flexible and scalable. For example, while QOZBs must be located in an Opportunity Zone, qualified investors may participate in the program regardless of where they live or work.
Where Are Opportunity Zones?
Qualified Opportunity Zones may be found in urban, suburban, or rural areas across all 50 states as well as Washington, D.C. and six of the 16 U.S. territories. Governors may nominate a census tract (or tracts) for Opportunity Zone classification, but the U.S. Department of the Treasury oversees the approval process. As of the summer of 2019, 8,764 individual census tracts have been certified as Opportunity Zones.
Texas is home to 628 Opportunity Zones. Only California (879) and Puerto Rico (865) outrank the Lone Star State in this capacity. Moreover, those 628 Opportunity Zones account for nearly 12 percent of Texas’ census tracts, or approximately half of the federally mandated maximum for the program. According to a recent report from the Austin Business Journal, a mere 13 other states “have a higher percentage of Opportunity Zones than Texas.”
Taking Stock of Opportunity Zones
Opportunity Zones have garnered a great deal of buzz in their brief lifetime. Shortly after the program’s creation, Treasury Secretary Steven Mnuchin announced that “there’s going to be over $100 billion dollars in private capital that will be invested in Opportunity Zones.” Yet the program’s relative immaturity also means that evidence of the resounding success Mnuchin predicted remains scarce. Nevertheless, a handful of statistics suggest that more and more investors are seriously investigating the benefits associated with Opportunity Zones.
- Over 280 “entrepreneurship incubators or accelerators” are currently operating within Opportunity Zones.
- According to the National Council of State Housing Agencies, almost 200 real estate funds were on pace to raise nearly $50 billion in capital earmarked for Opportunity Zones as of Q4 2019.
- More than $87 billion in Opportunity Zone-based raw land and development sites changed hands between 2018 and 2019. That figure represents a 14.6-percent increase over the year-and-a-half preceding the program’s creation and nearly matches the amount of similar investment made outside of Opportunity Zones.
- Multifamily properties are particularly hot. In the past 18 months, investment in apartment buildings, townhomes, condominiums, etc. in Opportunity Zones has risen sharply — just over 66 percent. During that same period, multifamily accounted for slightly more than half of all new Opportunity Zone construction (when measured by dollar value).
- In the last two months of 2019, total Opportunity Zone investments spiked by 40 percent. A December 31 funding deadline no doubt helped generate the $4.5 billion raised over those 60 days, but that number looks more impressive given the recent bad press Opportunity Zones have received.
What’s Holding Opportunity Zones Back?
Indeed, not all of the buzz about Opportunity Zones has been positive. Those skeptical of the program have characterized it as a “tax giveaway” for the wealthy that has done little to uplift economically depressed communities. Preliminary case studies even suggest that Opportunity Zones exacerbate the ill effects of gentrification. Whether Opportunity Zones are encouraging further investment in neighborhoods that have already experienced a significant influx of private capital or allowing current residents to grow equity and stay put largely depends on who is talking about this contentious issue.
The rules governing Opportunity Zones and Opportunity Zone investments are complex — to say the least — and not without loopholes. Some contend that these have been far too easy to exploit. For example, census tracts with high student population density often report higher unemployment and poverty rates, even though full-time students were never meant to be the primary beneficiaries of the program. In other instances, local power players have used Opportunity Zones as a cover for securing tax relief on their private holdings, including one now-infamous marina in West Palm Beach.
Worse, news stories such as the October report that convicted felon Michael Milken — a figure synonymous with Wall Street’s excesses of the 1980s — was actively lobbying for further relaxation of Opportunity Zone regulations have done little to silence the program’s critics.
Where Do Opportunity Zones Go From Here?
In November of 2019, Senator Ron Wyden of Oregon introduced the Opportunity Zone Reporting & Reform Act. True to its name, this bill would:
- Obligate QOFs to release more public information about their activities.
- Prohibit QOFs from investing in “sin list” projects such as stadiums, casinos, and luxury apartments.
- Eliminate the grandfathering of developments that were already in progress prior to Opportunity Zone designation.
- Rescind Opportunity Zone status awarded to any areas found not to have met the Census Bureau’s low-income criteria.
As of this writing, Wyden’s bill has not earned bipartisan support. It is unclear which, if any, of its provisions will become law. That said, most experts believe that the proposed reporting requirements stand the best chance of being ratified.
Congress is not the only entity prescribing treatments for the growing pains Opportunity Zones are experiencing. Newly minted regulations from the Treasury Department promise to reshape the program significantly, mainly by focusing on mitigating risk and improving transparency.
For example, these regulations will clarify who can benefit from the program’s tax breaks and would include businesses and start-ups funded by QOFs. Overall, the changes to the program are extensive, filling 544 pages of the Federal Register. From a strictly CRE perspective, among the most relevant changes to the program include the following.
- Updates to the original use test specifications. Now, buildings within any given Opportunity Zone need only to have been vacant for one year to meet the original use requirements, provided the building was unoccupied at the time of the Opportunity Zone’s designation. Buildings occupied at the time of designation must adhere to a vacancy period of three years.
- Easement of the program’s substantial improvement test. Within 30 months, QOFs must match their original property investment (basis) with spending on additions and renovations. Under the new rules, QOFs may aggregate buildings for this purpose.
- Redrawn boundaries. Census tracts and land parcels do not always align perfectly. Consequently, QOZBs can choose to apply either a square footage test or an unadjusted cost test to determine whether real property contiguous to but technically external to an Opportunity Zone may be incorporated within it.
- Reclaiming brownfields. One-third of all contaminated land in the U.S. is situated within Opportunity Zones. To spur reclamation of these sites, these new rules permit QOFs to factor in both land and structures when meeting the requirements for brownfield remediation.
What Does The Balance Sheet Tell Us About Opportunity Zones?
Are Opportunity Zones really a rising tide that lifts all boats? Perhaps not, or at least in their original form. That’s the conclusion drawn by one group of economists. Alan Sage (MIT), Mike Langen (Maastricht University), and Alex Van de Minne (University of Connecticut) examined Opportunity Zone commercial real estate transaction data to test two hypotheses.
- Tax incentives will directly increase an Opportunity Zone investor’s post-tax internal rate of return.
- Incentivized Opportunity Zone investments will boost productivity, cause land to appreciate, and generate other benefits beyond tax relief.
While Sage et al. found support for the first hypothesis, they did not for the second. The valuation data these scholars reviewed suggested that “only properties that benefit from the tax break — redevelopment properties and vacant land — see their prices increase [by 13.5 percent and 9.6 percent, respectively].” The net result? Opportunity Zones are best at “passing through the statutory tax benefits to existing landowners” who may or may not be members of the communities the program is intended to serve.
That said, the Opportunity Zone program does give those same communities another means of controlling their own destinies. Even under the revised rules, local governments have leeway to draft and implement their own best practices for interacting with QOFs and QOZBs. Policies that prioritize transparency, champion inclusivity, and cooperate with broader community and economic development strategies stand the best chance of deploying CRE to help Opportunity Zones achieve their goal: creating wealth in areas that have historically struggled with underinvestment.
Update, 01/30/2020: On January 15, 2020, NBC reported that the Treasury Department had launched a formal investigation into the Opportunity Zone program. The focus on this probe, prompted by an October 2019 letter from the legislators (Senators Cory Booker and Tim Scott) to Acting Treasury Inspector General Richard Delmar, will be on how Opportunity Zones are identified, nominated, and approved. In their letter, Booker (a Democrat) and Scott (a Republican) caution: “It was not the intent of Congress for this tax incentive to be used to enrich political supporters or personal friends of senior administration officials, as recent reports indicate.” (Meanwhile, the Senate Finance Committee has taken no further action regarding the Opportunity Zone Reporting & Reform Act.)
What does this investigation mean for Opportunity Zones long-term? Most experts are taking the “sunlight is the best disinfectant” point of view and view this as a positive development. Steve Glickman, who helped draft the 2017 legislation that created Opportunity Zones, points out that, “Even in the worst-case scenarios, you are talking about [abuses in] a couple [census] tracts out of about 8,700.” Glickman is confident the program itself will emerge from the Treasury Department’s investigation — which should be completed by early spring of this year — mostly intact. The bullishness of Opportunity Zone investors would appear to give further credence to such optimism. According to Novogradac, a public accounting firm that maintains a rolling survey of QOFs, 2019 ended on a very high note, with December Opportunity Zone funding up 50 percent (to $6.7 billion) from November.
That said, Opportunity Zones clearly remain a work-in-progress. Although barely three years old, the program has already been subject to significant rule changes. Stay tuned to LPA Insights as we continue to track the evolution of Opportunity Zones through 2020 and beyond.
Looking ahead.
It’s something we all do once the holiday season arrives. That includes the CRE valuation experts here at LPA.
Sure, we get giddy in the days leading up to the release of the latest market data, and we can barely contain our excitement when talking with our clients about appreciation trends.
But let’s be real: as soon as we shake off the lingering effects of that Thanksgiving food coma, we start counting the days until Christmas morning. We keep wish lists too, after all, and have since we first discovered our passion for real estate. Come to think of it, maybe Santa putting Barbie’s Malibu Dreamhouse, those bright yellow Tonka Trucks, and that Magic Math Machine under the tree had something to do with sparking that interest…
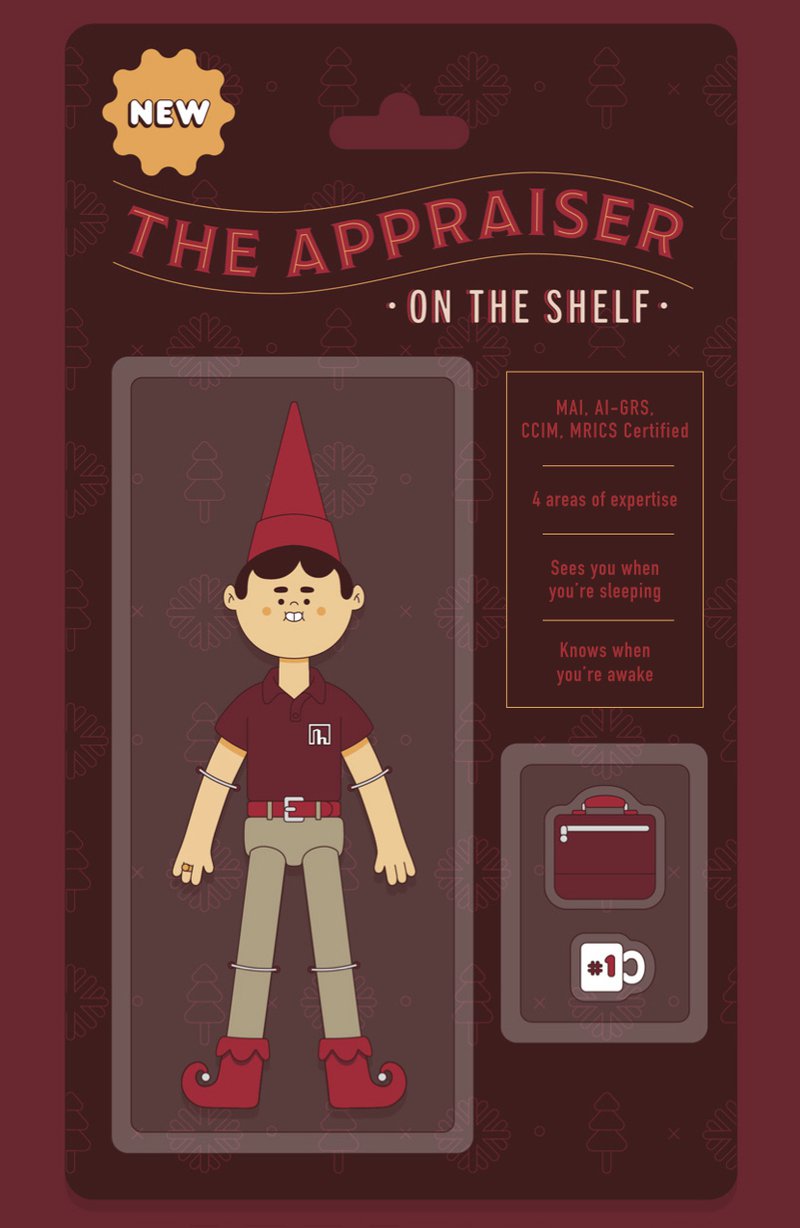
Anyway, that was then. This is now. This holiday season, the North Pole’s largest toy manufacturer (in terms of both square footage and throughput) can barely keep up with demand for one toy in particular. Without further ado, allow us to introduce you to the “Appraiser on the Shelf.”
Although he may be pint-sized, this professional comes complete with all the necessary certifications: MRICS, CCIM, even his AI-GIS and MAI designations*. In other words, he packs quite a resume — not to mention comprehensive property type expertise. (Although he does specialize in bookcases, cabinets, mantles, dressers, and desks.)
And when we say the “Appraiser on the Shelf” is relentlessly focused on delivering flawless, accurate, on-time valuations, we’re not kidding. He never sleeps. We suspect that bottomless mug has something to do with how quickly he can turn around a 90-page, USPAP-compliant appraisal report. Even if you do run out of coffee, however, you never have to worry about replacing his batteries. This elfin analyst is 100-percent powered by Christmas spirit. Shouldn’t we all be so lucky?
From the entire LPA Team, here’s hoping your holidays are full of special deliveries that bring you nothing but joy. Merry Christmas and Happy New Year!
* “Appraiser on the Shelf” is a toy, not an actual licensed appraiser. He is not qualified to give legal, CRE market, neighborhood, structural, or live advice. Contents of genuine leather briefcase may have shifted from nice to naughty during transport. LPA is not liable for any damages, loss of presents, or emotional stress sustained as a result of the toy coming to life with real Christmas magic.
Over the past decade, new products and services coming out of Silicon Valley have profoundly altered — and often improved — how we live, work, and play. But commercial real estate (CRE) is one area in which widespread adoption of advanced technology has lagged. Until recently, industry players have focused almost exclusively on refining the efficiency of already existing processes. In doing so, they have given short shrift to the digital disruptions rippling through residential real estate, from Zillow’s serving of aggregated housing data through its freely accessible website to Opendoor’s cutting multiple middlemen out of the home buying and selling processes.
But a group of up-and-coming startups is aggressively targeting CRE. Their aim is to dismantle existing infrastructure — the policies, procedures, ownership models, and basic materials that have made CRE a prohibitively expensive, illiquid, and relatively opaque asset class for many investors — and replace it with entirely new systems geared toward speed, scalability, and peak profitability. Collectively, these new systems constitute what is known as proptech, a unique and ever-shifting amalgamation of commercial real estate expertise and technological innovation.
What are those innovations, and how are they significantly changing how CRE is bought (or leased), at what price, and from whom?
Big Data
In its original context, the “big” in “big data” meant “astronomical.” That’s because the term was first coined by NASA scientists in 1997 as a way to describe collections of information so vast and dense that they can only be manipulated with machine assistance. “Big data” has since come to refer to the quantification of even the most everyday activities and interactions. If you’ve ever found yourself structuring your daily routine around breaking the 10,000-step threshold, then you’ve experienced “big data” firsthand.
In today’s CRE market, big data is producing unprecedented insights into building utilization. Landlords are monitoring and gathering data about everything happening in (and, in some cases, around) their properties. Once subjected to analysis, such real-time data on how people interact with buildings can inform systems that facilitate predictive maintenance, track energy consumption, manage vacancies, and bolster tenant retention using true customer relationship management (CRM) functionality.
With respect to valuation, big CRE data could be mined to reveal hidden portfolio risks and empower more proactive market strategies. It might also guide decisions regarding renovation and redevelopment, hypothetically increasing the revenue potential of any given property. Does more foot traffic pass through your clothing boutique on an east-west or north-south axis? Using people counters as well as indoor mapping and location services, retail property managers could conceivably optimize individual floor plans to achieve the highest possible sales volume per cash register — and thereby maximize the space’s rental value.
The Internet of Things (IoT)
The next (or fourth) industrial revolution is underway. On its front line are devices that aren’t robots per se but which come equipped with sophisticated computerized components. Thanks to inexpensive yet powerful processors and 5G wireless networks, practically any physical object can now be made “smart” — capable of independently transmitting streams of data about its status and the environment in which it is situated on an Internet of Things (IoT). Such devices currently outnumber the human residents of our planet, and their population is expected to climb to a staggering 20.4 billion by 2020.
Smart elevators. Smart HVAC systems. Smart building security systems that incorporate biometric recognition. Even smart plumbing systems whose pipes can alert property managers before they freeze and burst. These solutions are all currently available and, as they attain greater market penetration, will cease to be seen as premium. (Longtime CRE observers have seen this pattern before with green buildings.) Yet, whatever cool features these tools have to show off, can they pay for themselves? Can they even boost any given property’s market value?
The short answer is that it may be too soon to tell. However, according to a recent report issued by Memoori, “the combined global market for the Internet of Things in Buildings (BIoT) will grow significantly over the forecast period, rising from $26.65 billion in 2015 to $75.5 billion by 2021, at a CAGR [Compund Annual Growth Rate] of 20.7 percent.” Meanwhile, owners of multifamily properties should be aware that more than 75 percent of respondents to a survey conducted by Coldwell Banker and T3 Sixty indicated that they would be willing to pay more to live in a smart home. Property type considerations and tenant preferences aside, landlords may still realize significant cost savings by making smart, efficiency-generating upgrades and renovations.
Blockchain
Although synonymous with headline-grabbing cryptocurrencies such as Bitcoin, Ethereum, and Libra, blockchain technology has applications and implications far beyond the transactional. A comprehensive overview of the blockchain and how it works is beyond the scope of this article, but suffice it to say that virtually any CRE process that has traditionally relied upon a paper trail may ultimately be migrated to this automated and hacker-proof digital space. That’s because, unlike other forms of digital data, the “blocks” in any given blockchain can be distributed but not duplicated.
Smart CRE contracts that utilize the blockchain are already in use. These contracts are replacing customary lease agreements as well as transfers of title. In fact, title management may stand to benefit the most from the blockchain. The American Land Title Association estimates that fully one-quarter of all title records contain erroneous information, resulting in costly title resolution proceedings. Smart contracts could also be the key to eliminating title fraud.
From an appraiser’s perspective, the blockchain could combine with big data to make the verification of all property details both faster and more accurate. Everything from ownership history to repair records could be collocated in a centralized, blockchain-secured repository. And, as the blockchain propels CRE toward a future of fractional or tokenized ownership, valuation experts will likely have to rely more and more upon such repositories.
Of course, any investor who has ridden the Bitcoin rollercoaster might view the blockchain with healthy skepticism. Many unanswered questions about the technology and the consequences of its widespread adoption remain. As Data Nerds and Estated CEO Joshua Fraser writes in Forbes, the blockchain may “get rid of the need for banks, lawyers and other intermediary figures and instead validate transactions purely using digital encryption.” Whether that is a desirable state of affairs for investors, lenders, developers, contractors, property attorneys, appraisers, and the communities that rely upon a thriving CRE marketplace remains to be determined.
The Best of the Rest
Artificial Intelligence (AI). The Age of AI may still be dawning, but machine learning is already being profitably leveraged by CRE professionals. Computer programs that perform tasks that typically require human intelligence are already being used to normalize data (e.g., leases, nondisclosures, available inventory), locate key clauses or phrases in CRE-related documentation, identify incomplete or missing data, and simplify fiscal reporting. By automating and optimizing specific tasks that can be redundant and prone to error when handled by a human operator, AI is also providing a better foundation for decision-making. In the long term, software-based “robots” may indeed replace these human operators outright. In the short term, however, the process augmentation AI-powered systems provide is one factor in CRE’s recovery from the financial crisis of 2009.
Virtual Reality (VR). Despite the failure of the ‘90s-era VR products, VR’s time may have finally arrived courtesy of the CRE market. (VR sales are expected to reach $40.26 billion by 2020.) VR is a natural fit for the industry, as it enables investors to tour properties without time-consuming, expensive, and environmentally unsustainable travel between distant locations. Moreover, recent innovations in VR promise to make the technology more accessible to smaller, less high-end CRE developments.
Drone Technology. The extraordinary aerial imagery we enjoy today has been made possible through the use of drones. These remotely piloted devices can photograph everything from high-rise office buildings to coastal properties to sports stadiums. Visually impressive flyover videos can be instrumental in closing CRE sales, but they can also communicate valuable information — for example, surrounding due diligence.
The Texas State Legislature convenes only every two years. Such a schedule ensures that each session is a busy one, and the recently adjourned 86th regular legislative session was no exception.
According to one estimate, during that 140-day assembly (which began January 8 and ended May 27, 2019) legislators filed 7,795 bills and resolutions. Of those, only about 19.5 percent (1,525) reached Governor Greg Abbott’s desk, with slightly over 1,400 now scheduled to become law.
Of these 1,400 enacted measures, several pertain to real estate, both residential and commercial. Among them are four laws whose provisions could significantly influence how real property is valued, traded, and developed across the state.
Read on to learn more about the new real estate laws on Texas’ books, how they got there, and what their presence could mean for your business.
House Bill (HB) 2439: Prohibition of Local Government Product Mandates
- This legislation prohibits cities from using building codes or other local ordinances to require the use of construction products that exceed national standards.
- HB 2439’s bipartisan authors, sponsors, and supporters hope this measure will curtail a domino effect in which one requirement leads to the direct or indirect prohibition of otherwise approved construction products, thus creating significant compliance challenges for contractors — or effectively forcing them to work with a vendor they might not otherwise prefer.
- For example, authorities can no longer mandate masonry material percentages in new construction or limit contractors to using a single type of insulation, piping, or tubing if national model building codes permit other options.
- Elected officials representing several municipalities across Texas (including Dallas and McKinney) urged a veto of HB 2439, saying it fails to strike an adequate balance between financial and aesthetic considerations. They argue that the law penalizes communities by limiting their ability to designate conservation districts and preserve the character of their local architecture.
- However, the law does contain exceptions for neighborhoods officially registered as historically or culturally significant. This exception also includes commercial buildings located in downtown areas participating in the Texas Main Street Program (TMSP).
- Will the enrolled version of HB 2439 contribute to a decline in the quality and safety of construction, as its opponents fear? Or will it deliver on its chief promises: to provide consumers more choice when selecting building materials and make housing, especially multi-family dwellings, more affordable? Answers to these and other questions may be soon in coming, as the law has been in effect since September 1, 2019.
HB 2496: Historic Landmark Designation
- The stated purpose of HB 2496 is to protect individual property owners from what its authors deem to be unfair and inconsistent rules around the establishment of historic landmarks.
- HB 2496 stipulates that a municipality in Texas cannot name a property a historic landmark unless:
- the owner of the property consents to the designation; or
- the designation is approved by a three-fourths vote of the governing body of the municipality as well as the municipality’s zoning, planning, or historical commission.
- HB 2469 further stipulates that owners whose properties are subject to historic designation be issued a “historic designation impact statement.” Upon reviewing this official document, owners may withdraw previously granted consent.
- HB 2496 received the backing of the Home Builders Association of Greater Austin, among others. These proponents claim that historic designations unjustly strip property owners of their rights and devalue their real property investments. They cite the fact that even though landmark status does offer owners property tax relief, it may obligate them to undertake expensive repairs and saddle them with burdensome regulatory obligations.
- Organizations such as Preservation Austin, Preservation Texas and the National Trust for Historic Preservation contend that HB 2496’s requirements do more than make it difficult to save specific historic structures from either the wrecking ball or a landlord with a vision for modernizing such properties. These organizations believe the law all but prevents the creation of new historic districts, citing the virtual impossibility of securing approval under its strict provisions.
- Is a historic landmark more or less attractive to prospective buyers? The answer to this question varies by location, market (residential versus commercial real estate), and even property type. Whatever the case, the Texas Legislature has, with this law, clearly sided with current property owners and targeted what they consider overreach by local governments.
- HB 2469 was signed into law by Governor Abbott on May 25 and is effective as of September 1, 2019.
HB 347: Annexation
- This 2019 legislation revises SB 6, which was enacted in 2017.
- With SB 6, the 85th Texas Legislature separated the state’s counties into two tiers. Tier 1 counties — defined as having a population of less than 500,000 — were allowed to annex land at their sole discretion. However, Tier 2 counties — with a population of over 500,000 — could annex land only after holding an election in the area proposed to be annexed and winning the approval of a majority of the landowners.
- HB 347 abolishes this system. Now, all Texas counties are effectively Tier 2. Any municipality that wishes to annex land must put the proposal to a vote as specified above.
- Passed by super-majorities in both houses, this measure went into effect immediately after Governor Abbot signed it on May 24, 2019.
- Both the Texas Association of Realtors and grassroots supporters throughout the state hailed the law for putting an end to what they called “forced annexation.” One of the bill’s authors, Rep. Phil King, was encouraged to act by residents of a neighborhood is his home county (Parker) unwilling to be incorporated into the city of Weatherford, itself located just 25 miles west of Fort Worth.
- HB 347 has the potential to alter the pace of urbanization in Texas. Since 2010, Texas has welcomed over 1 million new residents from the other 49 states. Writing for The Dallas Morning News, Lloyd Potter, Texas’ official demographer, reveals that “the state’s metro regions garnered 94 percent of the total domestic migration between 2010 and 2014.”
- Urbanization has helped fuel Texas’ economic expansion over the past decade as well — as the health of the state’s CRE market indicates. For example, retail occupancy rates in Texas’ four largest metropolitan areas (Austin, Dallas-Fort Worth, Houston, and San Antonio) currently average 94 percent.
- The passage of HB 347 should serve as a reminder that property rights in Texas can be a particularly sensitive issue, especially as more of the state’s traditionally rural areas are faced with the choice of becoming suburbs and exurbs.
SB 2: Property Tax Reform
- This law, dubbed the Property Tax Reform and Relief Act of 2019, provides an automatic property tax rollback election if cities, counties and other local entities propose an increase of more than 3.5 percent.
- These increases cannot be scheduled for a special election and must be included on ballots issued during the state’s November general elections.
- Under previous legislation, voters could petition for a property tax rollback only if a proposed revenue increase exceeded 8 percent.
- The law also obligates the state’s Central Appraisal Districts (CAD) to conduct their business more transparently. Each CAD must now maintain a property value database that allows for public comments on proposed rate increases.
- Additionally, these databases must contain public hearing information so property owners can more easily appeal (or protest) the assessed (or taxable) value of their property.
- City officials in the state’s larger metropolitan areas expressed considerable opposition to SB 2. They fear that the measure, while a potential boon to individual taxpayers, will lead to critical budget shortfalls that will significantly limit their ability to maintain and expand essential services. They argue that those limitations could, in turn, slow future development and retard the growth of Texas’ economy.
- Supporters of SB 2 insist the lower rollback rate will help ease economic strain experienced by both homeowners and business owners.
- Leaders in the state’s CRE market have by and large championed SB 2. Considering that commercial property appraisal values in Houston (to take but one example) increased by nearly 40 percent in a five-year period ending in 2017, this should come as little surprise. But the financial implications of such a surge go beyond property tax bill sticker shock.
- Upward-trending property values become an issue for landlords when a property’s profitability cannot keep pace with its taxable value. Owners then have little choice but to pass the tax hike down to their tenants. When those tenants are businesses, they may choose to absorb that rent increase by cutting costs elsewhere — for example, by instituting hiring freezes or postponing (or even canceling) planned expansions.
- Nevertheless, cities such as Dallas and Houston have become desirable places to live, especially among millennials, due to their having made concerted urban revitalization efforts. While that revitalization does not happen without the private capital needed to build and renovate, it also takes the cooperation of local governments solvent and functional enough to maintain roads, collect garbage, and ensure public safety.
- The bulk of SB 2’s provisions will take effect on January 1, 2020.